UK Visitor Visa Bank Balance Requirements for Expats (Safe Funds Guide)
When applying from the Middle East, understanding the UK visitor visa bank balance requirements for expats is often the biggest source of confusion. The first question everyone asks is: “Exactly how much money do I actually need to show?
The truth is, the UK government (UKVI) does not have a fixed minimum amount. Having £3,000 or £5,000 in your account does not automatically guarantee your visa will be approved.
However, for expats living in the UAE, Saudi Arabia, Qatar, and the wider Gulf, proving financial stability is often the biggest hurdle. Most visa rejections happen not because you lack money, but because your bank statement looks unnatural.
Visa officers do not just look at your final closing balance. They want to see a logical match between your monthly salary, your regular living expenses, and the money you plan to spend on your UK holiday.
Here is a realistic formula to calculate how much you actually need to show:
| The Safe Bank Balance Formula for Expats |
|---|
| Your Target Balance = Total Expected UK Trip Cost + 2 to 3 Months of Your Regular Living Costs in the Gulf. |
| Example for a 7-Day UK Holiday: You should ideally show around £3,000 to £4,000 (roughly 14,000 to 19,000 AED/SAR/QAR) of untouched, genuine savings. |
If you are just starting your application and want to understand the basic rules and biometric steps, check out our complete UK visitor visa guide.
UK Visitor Visa Bank Balance Requirements for Expats: What Officers Check
Instead of looking for a specific magic number, UK visa officers look at your financial history to see if your story makes sense. They focus on three main things:
- Where the money came from: Every dirham or riyal in your account must have a clear source. The officer wants to see your regular salary deposits, clear business income, or proper end-of-service benefits. Unexplained cash drops look highly suspicious.
- Does the trip cost make sense? If you are planning to blow six months of your hard-earned savings on a simple five-day vacation, the officer will doubt your true intentions. Your travel budget must be a realistic fraction of your total savings.
- Money left over for daily life: After paying for your UK flights, hotels, and daily meals, do you still have enough money left in your account to pay your rent and buy groceries back in the Gulf until your next payday? If your account drops to zero, it is a massive red flag.
If your recent bank statements show sudden, large cash deposits that are outside your regular salary, you must explain them clearly. You can learn exactly how to handle this in our guide on how to explain large cash deposits for a UK visa.
The “3x Monthly Savings” Rule for Gulf Expats
Visa officers use a very simple calculation to check if you can actually afford the trip. They look at your “disposable income.” This is the money left in your account every month after paying your rent, groceries, credit card bills, and sending money back home to your family.
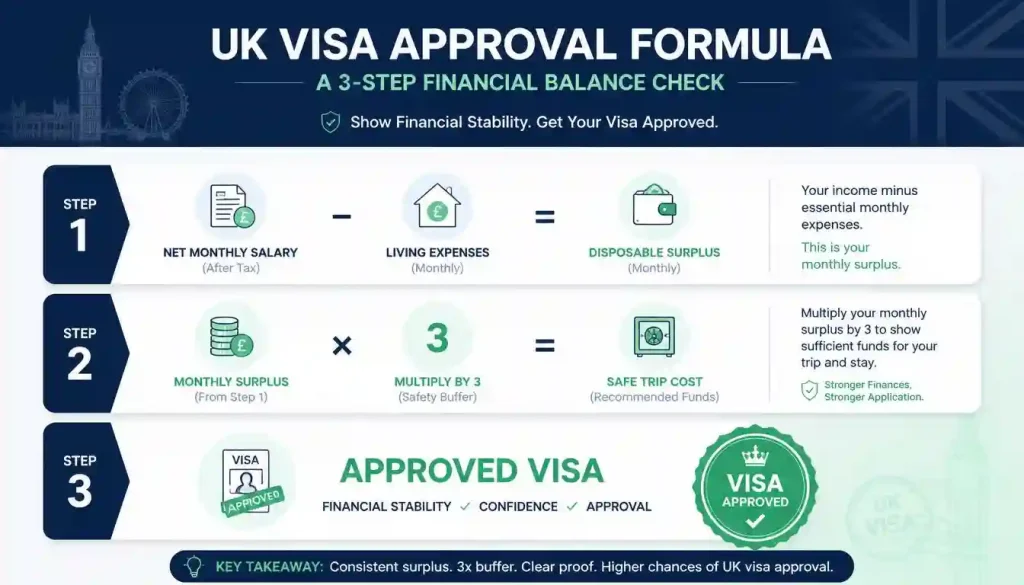
As a general rule, your total UK holiday should not cost more than three times your monthly leftover savings. Here is a realistic example of how an officer calculates this for an expat living in Dubai:
| Financial Check | Example (Dubai Expat) | What the Visa Officer Thinks |
|---|---|---|
| Monthly Take-Home Salary | 12,000 AED (~£2,500) | Good, stable legal income. |
| Monthly Living Costs & Remittances | 8,000 AED (~£1,650) | Normal living expenses in the UAE. |
| Monthly Leftover Savings | 4,000 AED (~£850) | This is your true saving capacity. |
| Cost of 7-Day UK Trip | 8,500 AED (~£1,750) | Safe. It equals about 2 months of savings. |
| Total Bank Balance Shown | 22,000 AED (~£4,500) | Approved. Plenty of money left for emergencies. |
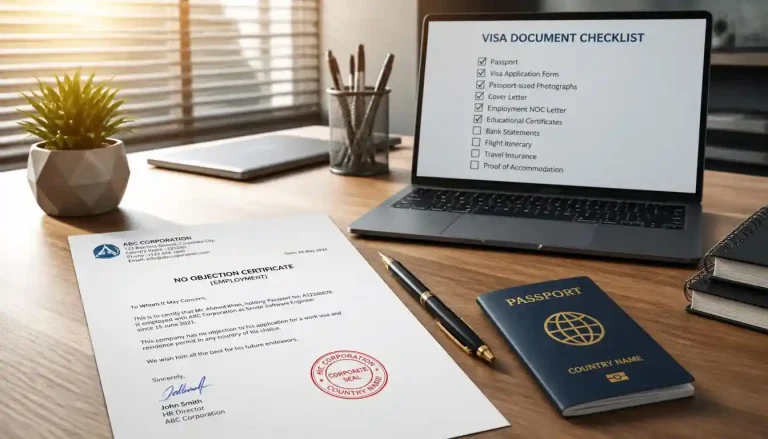
If you only save 1,000 AED a month but plan a 15,000 AED holiday, the officer will assume you cannot really afford it. To prove your job is secure and your salary will continue after you return, you must attach a proper leave approval letter. You can follow our UK tourist visa NOC and employment letter format to get this exactly right.
Expected Bank Balance by Gulf Country
Living expenses are very different across the Middle East. A UK visa officer knows that surviving in Dubai costs much more than living in Oman. Because of this, what looks like a “good” bank balance changes depending on where your residency is based.
Here is a general guide on what visa officers expect to see in your account, along with the most common mistakes applicants make in each country:
| Country of Residence | Typical Expat Salary | Safe Bank Balance | Biggest Red Flags for Visa Officers |
|---|---|---|---|
| UAE (Dubai / Abu Dhabi) | 8,000 – 15,000+ AED | 16,000 – 25,000 AED | Cash deposits that do not come through the WPS system. |
| Saudi Arabia (Riyadh / Jeddah) | 7,000 – 14,000+ SAR | 15,000 – 22,000 SAR | The salary in the bank does not match official GOSI records. |
| Qatar (Doha) | 7,500 – 13,000+ QAR | 15,000 – 20,000 QAR | Unexplained wire transfers coming from outside the country. |
| Kuwait / Bahrain / Oman | 650 KWD / 850 BHD / 800 OMR | 1,400 KWD / 1,800 BHD / 1,800 OMR | Suddenly depositing a large amount of money right before applying. |
Bank Statement Rules for UAE Residents
If you are applying from Dubai, Abu Dhabi, or anywhere in the UAE, visa officers will strictly check your bank statements against the government’s Wages Protection System (WPS).
Here is what you must ensure to avoid a quick rejection:
- Official Company Name: Your monthly salary deposit must clearly show your employer’s registered company name. If your salary comes in as a direct cash deposit or a transfer from an individual’s personal account, the officer will not accept it as legal income.
- No Crypto or Trading Apps: Do not show your travel funds in crypto wallets or stock trading apps. Visa officers only accept standard, easy-to-access current or savings accounts registered under your exact passport name.
Bank Statement Rules for Saudi Arabia Residents
If you are applying from Saudi Arabia, UK visa officers will cross-check your bank deposits with your official GOSI registration and Chamber of Commerce contract.
Here is how to avoid the most common rejection trap in KSA:
- The GOSI Mismatch Problem: It is very common for expats to have a lower “base salary” registered in GOSI, while receiving a much higher total salary in the bank due to housing and transport allowances. For example, your GOSI might show 5,000 SAR, but your bank receives a net deposit of 12,000 SAR.
- How to Fix It: Do not let the visa officer guess where the extra money came from. You must attach an official, stamped salary certificate from your employer. This letter must clearly break down your base pay plus all extra allowances, proving exactly why the final bank deposit is higher than your official GOSI record.
How to Estimate a Realistic UK Trip Budget
When you fill out your visa application, you have to write down exactly how much money you plan to spend. The visa officer will check if your numbers are realistic. If you claim you will only spend £20 a day in central London, they will immediately know your budget is fake.
Here is a rough idea of what things actually cost in the UK right now:
- London Hotels: Expect to pay between £120 and £200 per night for a standard 3-star room in Central London.
- London Daily Expenses: Budget around £50 to £80 per adult, per day to cover food, coffee, and riding the London Underground (Tube).
- Outside London (Manchester, Scotland, etc.): Hotels are generally cheaper here, ranging from £85 to £140 per night. Your daily food and local transport will cost around £40 to £60.
- Staying with Family or Friends: If you are staying rent-free with someone living in the UK, your required bank balance will drop significantly. However, your host must provide a formal invitation letter to prove you have a place to stay. To see exactly what papers they need to send you, check out our guide on UK visit visa sponsorship letters and financial proof.
Handling Complex Bank Statements as an Expat
Living as an expat means your banking setup might be a bit more complicated than someone applying from their home country. Here is how to present your finances clearly so the visa officer does not get confused:
1. Using Multiple Bank Accounts
Many expats receive their salary in one account and keep their savings in another. This is perfectly fine, but you must handle it carefully to avoid confusion.
Here is what you need to do:
- Submit Both Statements: Always provide the full 6-month statements for both your salary account and your savings account.
- Avoid Sudden Transfers: Never move all your savings into your main account just a few days before applying. Visa officers hate this and will immediately suspect you are faking your balance.
- Explain Your Habit: If you regularly move money between your accounts every month, just add a short sentence in your cover letter explaining these normal internal transfers.
2. Currency Conversion to British Pounds (GBP)
Your bank statements will naturally be in your local Gulf currency. However, the visa officer will calculate your entire budget in British Pounds (GBP).
Here is exactly how to handle this:
- Use the Official Tool: Calculate your expected trip costs using the official OANDA Currency Converter. This is the exact website UK visa officers use.
- Show Your Proof: Exchange rates change every day. On the day you apply, print the OANDA conversion rate page or clearly mention the exact rate in your cover letter.
- Keep a 10% Buffer: Always keep at least 10% extra cash in your account. This protects your application if the exchange rate drops while you wait for a decision.
3. Expiring Residency IDs (Iqama, Emirates ID, or Civil ID)
As an expat in the Gulf, your residency card is just as important as your bank statement.
- The 3-Month Rule: Your Emirates ID, Saudi Iqama, or Kuwaiti Civil ID must remain valid for at least 3 to 6 months after you return from your UK holiday.
- The Expiry Red Flag: If your ID expires within a few weeks of your travel date, the visa officer will easily suspect you are going to the UK to stay and look for work.
- Physical ID Check: Always bring your original, physical ID card to the visa center. To see exactly what else happens on that day, check out our guide on what to expect at your UK visa VFS biometrics appointment.
Why Visa Officers Reject Bank Statements
Even with a good bank balance, many expats get their visas refused for a few simple mistakes. Here are the biggest red flags you must avoid:
- Never Borrow Money: Do not ask friends or family to transfer a big amount of money into your account just before you apply. Visa officers know this trick well. They will immediately reject your application for “fund parking,” and you will lose your visa fee.
- Sending Money Back Home: If you regularly send money to your dependents in your home country, be honest about it on your application form. If you claim you have zero monthly expenses, but your bank statement shows regular international transfers, the officer will think you are hiding the truth.
- Mismatched Payslips: The salary amount on your company payslip must perfectly match the salary deposited into your bank. If your payslip says 12,000 AED but your bank statement only shows 11,500 AED down to the exact digit, it will raise an instant red flag.
FAQs
How many months of bank statements do I actually need?
The official UK rule says 3 months. However, if you are applying as an expat from the UAE, Saudi Arabia, or Qatar, you should always submit 6 months of statements. This clearly proves your job is stable and shows a normal pattern of how you save and spend over a longer period.
Does my credit card limit count towards my bank balance?
No, it does not. Visa officers only care about the actual cash you have in your checking or savings account. A high credit card limit shows you have good financial standing, but it cannot be used as proof of your travel funds.
Can I show Fixed Deposits (FD) or mutual funds instead of a bank balance?
You can attach them as extra proof of your overall wealth, but they cannot replace your normal bank account. Your main account must still have enough ready cash to cover your flights, hotels, and daily food. Visa officers know you cannot easily spend a locked fixed deposit while traveling in London.
What if my employer pays my salary in cash?
This is a major risk for a UK visa. If your company pays you in cash, you must deposit that exact cash amount into your bank account on the same day every month. You will also need to attach official, stamped payment vouchers from your company to prove where the cash came from.
Can I use my husband or wife’s bank statement for my application?
Yes. If your spouse is paying for your holiday, you do not need a big balance in your own account. You can use their bank statements. Just make sure to include a clear sponsorship letter from them, a copy of their passport, and your marriage certificate to prove the relationship.
Official References & Source Guidelines
- UK Visas and Immigration (UKVI): Official immigration rules on genuine visitors and financial viability under Appendix V: Visitor Rules.
- GOV.UK: Legal framework and entry clearance prerequisites outlined in Standard Visitor Visa Eligibility Guidance.
- HM Revenue & Customs / Home Office Exchange Standard: Foreign exchange conversion rates and valuation benchmarks via OANDA Historical & Live Currency Tools.